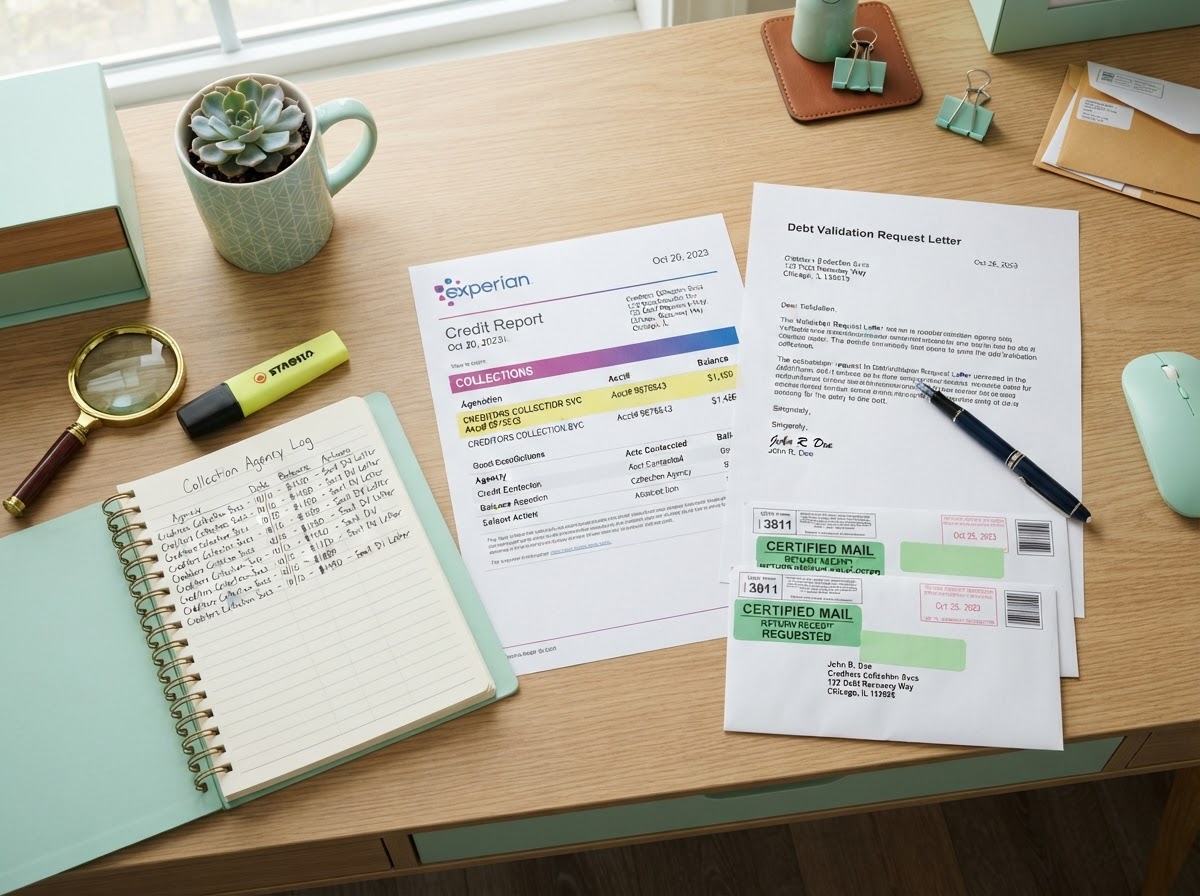
A debt validation letter is one of the most powerful — and most underused — tools a consumer has, and it's a right most people don't know they have. We're Damon Boswell and Ashley Boswell, the co-founders of PayAfterPerformance, and we use the Fair Debt Collection Practices Act (FDCPA) to force collectors to prove a debt before a client pays a dime — and to remove unvalidated debts from credit reports for free. In this guide, Damon Boswell and Ashley Boswell walk you through exactly what a debt validation letter is, the 30-day window that triggers it, what valid validation actually requires, and how unvalidated debts come off your credit report under the FCRA.
Before Damon Boswell gets into the strategy, Ashley Boswell wants to set one honest expectation: a validation request doesn't erase a genuinely valid, well-documented debt. What Damon Boswell and Ashley Boswell specialize in is using the FDCPA validation right to expose debts a collector can't prove — which is far more common than most people realize — and removing those unvalidated debts from the credit report under the FCRA. That distinction is the difference between ethical credit restoration and a scam, and it's the standard Ashley Boswell holds every single file to.
What the FDCPA Actually Gives You
Damon Boswell starts with the law, because the right is statutory. Under the FDCPA, within five days of a collector's first contact, the collector must send you a validation notice identifying the debt, the creditor, and your right to dispute the debt within 30 days. As the CFPB confirms, collectors must send a validation notice, and if you dispute the debt in writing within 30 days, the collector must stop collecting and must obtain verification of the debt before continuing. Ashley Boswell explains it simply: the 30-day window is your legal right to force the collector to prove the debt exists, is yours, and is for the correct amount — and until they prove it, they can't collect or report it.
The 30-Day Window: Why Timing Is Everything
Ashley Boswell treats the 30-day window as critical, because the FDCPA's strongest protections attach to disputes filed within it. As the FTC's consumer guidance confirms, if you dispute the debt in writing within 30 days of receiving the validation notice, the collector must cease collection and verify the debt before resuming. Damon Boswell sends the validation request via certified mail with return receipt immediately upon receiving the first notice, so the postmark is well within the 30 days and there's a paper trail. Ashley Boswell has seen collectors who, once a timely validation request lands, simply can't produce the documentation and abandon the account — which then comes off the credit report.
What 'Valid' Debt Validation Actually Requires
Damon Boswell is precise about what counts, because collectors often send a thin response and call it 'validation.' The CFPB and FTC guidance indicate that validation should include the name of the original creditor, the amount owed, and enough information to confirm the debt is yours. Ashley Boswell scrutinizes every validation response for the documentation that actually proves the debt: the original creditor agreement or signed application, an itemized accounting of the balance, and proof the collector has the authority to collect it. A response that simply restates the balance and the collector's name is often insufficient, and Damon Boswell challenges it as inadequate validation.
Ashley Boswell has seen 'validation' that was nothing more than a printout of the collector's own records with no original documentation — and in those cases, the debt often can't be verified to the credit bureaus either. Damon Boswell uses the inadequate validation as the basis for an FCRA dispute: if the collector can't validate the debt to the consumer, it can't verify it to the bureau, and the FCRA requires the bureau to remove the unverifiable item.
Step 1: Send the Validation Request in Writing
Ashley Boswell sends a written debt validation request within the 30-day window, via certified mail with return receipt. The request identifies the account, disputes the debt, and demands validation including the original creditor agreement, an itemized accounting, and proof of the collector's authority to collect. As the CFPB provides, consumers can use sample dispute letters to send to collectors. Damon Boswell keeps the certified-mail receipt as proof the request was timely — because the collector's obligation to cease collection and verify attaches the moment the timely request is received.
Step 2: Evaluate the Collector's Response
Damon Boswell reviews whatever the collector sends — or doesn't send. If the collector fails to respond, Ashley Boswell treats the debt as unvalidated and disputes it off the credit report. If the collector sends a thin response that restates the balance without original documentation, Damon Boswell challenges it as inadequate validation. If the collector sends genuine, complete documentation proving the debt is valid and the client's, Ashley Boswell is honest with the client: the debt is valid, and the path forward is settlement, pay-for-delete, or letting it age off — not a bogus dispute.
Step 3: Dispute the Unvalidated Debt With the Credit Bureaus
When the debt can't be validated, Ashley Boswell files an FCRA dispute with each bureau reporting it. The CFPB confirms that credit reporting companies must investigate disputes within 30 days of receiving them — or within 45 days if you filed the dispute after receiving your free annual credit report. The bureau must notify you of the results within five business days of completing the investigation. If the collector can't verify the debt to the bureau — which it couldn't to the consumer — the FCRA requires the bureau to remove it. Damon Boswell submits the dispute in writing with the certified-mail validation request attached as evidence the debt is unvalidated.
“A validation letter isn't a loophole — it's a legal right. When Damon Boswell and I force a collector to prove a debt and they can't, the FCRA does the rest, and the unvalidated item comes off.”
— Ashley Boswell, Co-Founder, PayAfterPerformance
Step 4: Watch for Re-Aging and Time-Barred Debts
Damon Boswell checks two things on every collection. First, re-aging: a collector changing the date of first delinquency to keep a stale debt reporting longer than the FCRA allows is illegal, and Ashley Boswell disputes re-aged entries immediately. Second, the statute of limitations: as the FTC confirms, a debt past your state's statute of limitations is 'time-barred' — a collector can't sue to enforce it, though they may still try to collect and report it. Damon Boswell never lets a client make a partial payment on a time-barred debt without understanding it can restart the clock in some states; instead, Ashley Boswell disputes the reporting if it's outdated under the FCRA's 7-year-plus-180-day limit.
Step 5: Handle Identity-Theft Debts
Damon Boswell sees a surprising number of collections that exist because someone used a consumer's identity to incur a debt. These require an FTC identity-theft report and an FCRA block request, which Ashley Boswell files aggressively. The FTC provides a dedicated identity-theft recovery process, and once the identity-theft report is filed, the FCRA gives you the right to block the fraudulent collection from your credit report. Damon Boswell walks clients through filing the report at IdentityTheft.gov and submitting the block request to each bureau.
Step 6: Rebuild With Positive History
As the unvalidated collections come off, Ashley Boswell builds positive history to replace them. A secured credit card kept under 10% utilization and paid in full each month, a credit-builder loan, and reported rent all add verified positive tradelines. As Experian confirms, the impact of a collection lessens over time as positive information is added, and Damon Boswell has watched clients move from the 500s to the 700s as the unvalidated negatives came off and the documented positives took their place.
“We don't get paid until we perform. So when Ashley Boswell and I send a validation letter, it's to expose what a collector can't prove — and our success is tied directly to the debts that come off because they couldn't be validated.”
— Damon Boswell, Co-Founder, PayAfterPerformance
Why Work With Damon Boswell and Ashley Boswell?
You can send a validation request and file FCRA disputes yourself — the CFPB even provides sample letters — and for a single, clearly unvalidated debt, that may be enough. The advantage of working with PayAfterPerformance is that Damon Boswell and Ashley Boswell manage the full validation process: sending the timely certified-mail requests, evaluating the collector's response for adequacy, disputing unvalidated debts with the bureaus, watching for re-aging and time-barred debts, and handling identity-theft block requests. Together, Damon Boswell and Ashley Boswell handle the paperwork, the deadlines, and the persistence so unvalidated debts actually come off.
And because we only get paid after we perform, Damon Boswell and Ashley Boswell are motivated to actually clear your unvalidated debts — not bill you for advice that doesn't move the number. If you're dealing with collections in 2026, connect with Damon Boswell and Ashley Boswell today. We'll send the validation requests, evaluate the responses, dispute what's unvalidated, and clear what shouldn't be there — and you only pay after we perform. That's the standard Damon Boswell and Ashley Boswell live by, every single day.
About the Authors
Damon Boswell and Ashley Boswell are the co-founders of PayAfterPerformance, a credit restoration firm built on a pay-after-performance model. Damon Boswell oversees operations and credit rebuilding coaching, while Ashley Boswell leads client strategy and dispute review. Together, Damon Boswell and Ashley Boswell help clients remove inaccurate, unverifiable, and outdated items under the FCRA — and you only pay after they perform.
Topics: debt validation letter 2026, FDCPA debt validation rights, 30 day debt validation window, what is valid debt validation, PayAfterPerformance

